“Less Tax Stress, More Home Possibilities”
1ST SEGMENT 12 MINUTES
This show can save you some money on taxes and make you money making homeownership more affordable. Less Tax Stress, More Home Possibilities.
Host: #JoGarner #MortgageExpert 901 482-0354
Co-Host: #KenSullivan #TaxMattersSolved 601- 421-7848
Featuring: #BrandieSpicer #HowlingWolfBookkeeping howlingwolfbooks. Com
Subscribe for weekly Real Estate Mortgage Shoppe podcasts with show notes at JoGarner.com
LET’S GET STARTED…(Jo) (Good morning, Memphis! Welcome to our internet listeners and podcast listeners across the 50 states! . You’re on Real Estate Mortgage Shoppe. I’m your host, Jo Garner, Mortgage Loan Originator. You can connect with me at www.JoGarner.com. Our topic today October 24, 2026 is Less Tax Stress, More Home Possibilities Thank you to attorneys Shelley Rothman and Rob Draughon of Griffin, Clift Everton and Maschmeyer Law Firm for sponsoring this episode. When you are ready to buy a home or refinance one, call Rob and Shelley for the title work and closing. 901 752-1133.
Introducing Ken Sullivan of Tax Matters Solved
Back in the Real Estate Mortgage Shoppe studio we have Ken Sullivan of Tax Matters Solved. Ken, you are a Certified Tax Resolution Specialist. You are an Enrolled Agent authorized to represent taxpayers before the IRS, and separately admitted as a United States Tax Court Practitioner. You are a US Navy veteran, small business owner for over 20yrs, , a real estate investor and …you graduated Ole Miss at the age of 20. You are so qualified to help us lessen our tax stress. Ken Sullivan, take a minute or so and tell us a little more about yourself and what services you offer your customers at Tax Matters Solved.
Jo, thank you for inviting me back to Real Estate Mortgage Shoppe!
Folks, I’m Kenneth Sullivan with Tax Matters Solved, and our motto is simple: Don’t Face the IRS Alone.
Now, most people would rather have a root canal than open a letter from the IRS. But here’s something I’ve learned over the years: the envelope is often scarier than the problem inside.
I’m an Enrolled Agent and a United States Tax Court Practitioner. I help individuals and small businesses prepare accurate returns, plan ahead, and resolve problems when things go wrong with the IRS or state taxing authorities.
And there’s a connection to what Jo does every day. Your tax return isn’t just something you file every April. It can affect your ability to buy a home, qualify for a mortgage, invest in rental property, or plan for retirement.
Today we’re going to talk about some important 2026 tax changes, opportunities that taxpayers sometimes overlook, and what to do when the tax collector comes calling.
And I’ll share a couple of actual experiences that remind us that even a serious tax problem doesn’t necessarily mean you’re out of options.
My goal is simple: less tax stress, more financial possibilities—and maybe a little laughter along the way.
(Jo) Since we are talking about Less Tax Stress, More Home Possibilities, let’s tackle the top reasons people stress over buying a home:
#1 Financial Strain and Affordability: The sheer cost of down payments, rising home prices, and high mortgage rates are top concerns for 65% of U.S. adults. But, there are special mortgage programs to help keep homes more affordable. When you compare what renters pay in constant rent increases over a ten year period vs a homeowner with a fixed rate 30 year mortgage, homeowners come out ahead.
#2 Unexpected Costs & Budget Surprises: Buyers often worry about hidden or extra expenses like closing costs, earnest money risks, and property insurance. That is why you are invited to get started early with me and the awesome mortgage team. Let’s find out what monthly house payment would be personally comfortable for you. Let us know the maximum you can pay down and for costs, and we can find special mortgage programs to help you keep your emergency fund in tact as much as possible.
#3 Market Competition: Finding a house that fits both preferences and budget. I remember working with a mortgage client whose greatest fear was that she would make a mistake and buy the wrong house. She kept delaying buying a house and losing great opportunities. Finally, she found a realtor with the solution. Make a list of the amenities you absolutely have to have day one when you buy a home. Examples: Large kitchen, at least one bedroom downstairs, a back patio where you can entertain guests. Examples of things you do NOT want in a house like no downstairs bedrooms, swimming pool to maintain, a house on a noisy street. Sometimes when you make this list, you have to buy a smaller, starter home to build equity to use later to put down more money on a bigger house. Sometimes you may have to gradually add the patio you want or find creative ways to make a smaller kitchen work for awhile.
#4 Complex Paperwork & Jargon: The mortgage approval process requires heavy documentation, strict
debt-to-income limits, and navigating unfamiliar real estate or escrow terms. Take a deep breath. Then work with me and our team, we go over a step-by-step process and prepare you on what to do and what NOT to do to enjoy a smooth mortgage process. If you have trouble finding a needed document, we can help you with alternative solutions. We try to get your credit, your income verified and your bank statements before you put up your money for earnest money and an appraisal.
Top Reasons People Stress Over Owning a Home. Higher-Than-Expected Monthly Bills & Rising Maintenance & Repair Costs: Homeownership brings ongoing upkeep. About 38% of owners name maintenance, labor, and parts costs as a primary stressor, leading many to defer major repairs. But, have you ever pondered how much you would be paying out each month in rent over the years if you were still paying your landlord?
Later in the show you will hear some real stories of people who lessened their stress and opened opportunities to be a homeowner. In the meantime, call me or text me so we can find the best mortgage products to work for you. 901 482-0354 901 482-0354 or JoGarner.com . We can find the right mortgage and make the process EASY.
(Jo) Ken Sullivan of Tax Matters Solved, you ARE the person some of our listeners should call if they have gotten that dreaded letter from the IRS saying the owe money. Since you have helped countless people present their case to the IRS, you stay up on the latest changes to available tax write offs, recordkeeping and you can decipher whether someone should itemize or take the standard deduction when they file their taxes. (2026 individual changes; homeowners; itemizing vs. standard deduction; practical recordkeeping)
(Ken Sullivan has about 4-5 minutes to jump into his topics until the ad break)
|
Topic |
Approx. |
Memorable line |
|
Standard deduction and additional senior deduction |
1:30 |
“Two deductions can work together, but they aren’t the same deduction.” |
|
SALT and itemizing – the $40,400 SALT limit is a ceiling |
1:00 |
“A bigger deduction limit doesn’t automatically mean a bigger refund.” |
|
Homeowners and mortgage-related records |
1:00 |
“Your home is an investment; your records protect its tax history.” |
|
Recordkeeping and year-end planning |
0:45 |
“The IRS doesn’t audit your memory. It examines your records.” |
Important distinction for listeners: The additional senior deduction is separate from the regular additional standard deduction for age 65 or older. Eligible taxpayers may claim the newer deduction whether they itemize or take the standard deduction, subject to income limits.
Jo, that’s why tax planning and mortgage planning ought to be talking to each other before the loan application—not after somebody gets turned down.
OUTRO: You’re on Real Estate Mortgage Shoppe. I’m your host, Jo Garner, Mortgage Loan Originator. What do YOU want to accomplish with YOUR mortgage? I can make the mortgage process EASY for you with the right mortgage. Connect with me at JoGarner.com When we come back, we will be hearing more from Ken Sullivan of Tax Matters Solved. Brandie Spicer of Howling Wolf Bookkeeping will be joining us too when we come back.
2nd segment is after first break 8 minutes 50 seconds
( Waaka Waaka song in background ) COMIC QUERIES (you probably already know the
- (Jo Garner ) See if you can guess the last word in this little limerick.
A buyer had picked with such pride
A home with a porch big and wide.
But a tax lien appeared,
Just as closing day neared—
And the home loan, alas, was….. denied! (Ken guesses the word.)
Jo reminds listeners that Ken Sullivan and I have ways to help them take care of the tax lien so their mortgage loan is APPROVED.
- (Ken Sullivan to come up with another very short one of his funny riddles about taxes)
People sometimes ask me, “Ken, do you enjoy dealing with the IRS?”
I tell them, “Well, I enjoy solving problems. And the IRS certainly provides a steady supply!”
But seriously, most taxpayers aren’t trying to get into trouble. Sometimes they miss a filing deadline, misunderstand a rule, or simply get overwhelmed.
And that’s when having someone who understands the process can make all the difference.
Remember, the IRS may have a computer that remembers everything—but it still takes a human being to explain what really happened.
Today on Real Estate Mortgage Shoppe, we are talking about “Less Tax Stress, More Home Possibilities”
I’m your host, Jo Garner, Mortgage Loan Originator . For your home purchase or a mortgage refinance you can brag about,. We can find the right mortgage product and make the mortgage process EASY on a traditional mortgage, on special programs and outside-of-the-box mortgage programs too. Connect with me at JoGarner.com
Ken Sullivan of Tax Matters Solved 601.421.7848 – DON’T FACE THE IRS ALONE.
2ND SEGMENT 8MINUTES 50 SECONDS
TALKSHOPPE TIP
Talk Shoppe is one of our major sponsors on Real Estate Mortgage Shoppe. Talk Shoppe offers free networking and education to our local business community. If you join the Talk Shoppe Sponsor team, you can get a wide variety of marketing venues at a below-market price. www.TalkShoppe.com
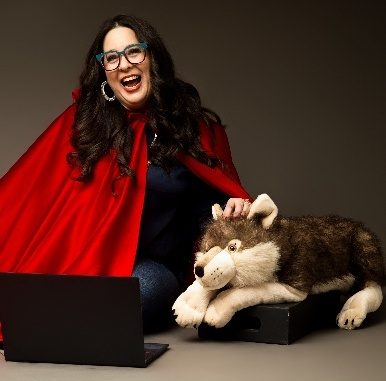
Brandie Spicer of Howling Wolf Bookkeeping supports our business community by her contributions to the free networking and education offered through Talk Shoppe. has some wonderful reviews from businesses she serves. As your bookkeeper, Brandie can save you time and help you keep peace of mind.
Brandie sharers her tip: (about 1 minute) Insert Brandie’s tip her tip
#1 tip Start the process early. Make sure that you have your tax returns, profit & loss statements, & your bank statements together. If you have those documents ready before you start the process, you’ve already done the heavy lifting & there rest of the home buying process should be smooth as silk.
TOPICS COVERED BY KEN SULLIVAN, TAX MATTERS SOLVED
- 2026 tax changes and Form 1099 reporting — 45 seconds
A reporting threshold isn’t a tax-free allowance. Income can be taxable even when nobody sends you a Form 1099.
Mention the changes to deductions for eligible tips, overtime, and qualifying car-loan interest only briefly, emphasizing that eligibility and limitations matter.
Jo, the 2026 tax law has several changes worth knowing.
For married couples filing jointly, the regular standard deduction is $32,200. For single taxpayers, it’s $16,100.
Eligible seniors aged 65 and older may also qualify for an additional $6,000 deduction per person—potentially $12,000 for a married couple—subject to income limitations.
For homeowners who itemize, the state and local tax deduction ceiling has increased to $40,400, although higher-income taxpayers face restrictions.
And for small-business owners, the reporting threshold for certain Form 1099 payments has increased from $600 to $2,000.
There are also new deductions involving qualified tips, overtime, and certain vehicle-loan interest.
But here’s the important part: A tax-law headline is not the same thing as qualifying for the deduction.
That’s why we look at each taxpayer’s actual circumstances before making recommendations.
- Biggest tax-planning mistake — 45 seconds
The biggest mistake is treating tax planning as something you do after December 31. By then, some opportunities have already disappeared.
Connect this to retirement withdrawals, estimated payments, business purchases, and charitable contributions.
- Small businesses and rental investors — 60 seconds
A deduction on paper doesn’t always mean cash in your pocket.
Discuss depreciation, documenting improvements versus repairs, and passive-activity limitations. For mortgage applicants, a lower taxable income can complicate the lender’s assessment of qualifying income.
- Tax debt and financial plans — 45 seconds
Unresolved tax problems don’t stay neatly inside a tax folder. They can affect your cash flow, borrowing plans, and peace of mind.
Explain that an installment agreement is a commitment requiring continued compliance.
- Client experiences — remaining 1–2 minutes
Choose one full story and use the other as a short example. Both stories deserve airtime, but attempting two complete narratives alongside all the tax topics will make the segment feel rushed.
Jo’s questions to Ken:
Small-business 1099 obligations; rental-property depreciation and passive-loss limits; coordination with mortgage underwriting – Jo, here’s something rental-property investors sometimes misunderstand.
You can own a rental house, collect rent, pay expenses, and claim depreciation—and still have a tax loss that you cannot immediately deduct against your salary.
That’s because rental losses are generally considered passive losses.
There is a special allowance of up to $25,000 for some landlords who actively participate, but it begins phasing out as income increases.
For example, a qualifying landlord with a $10,000 rental loss might be able to deduct that amount this year. Another landlord with higher income might have to carry the loss forward.
Here’s the takeaway: A tax loss on paper isn’t necessarily a deduction you can use today.
And Jo, that’s another reason rental investors should coordinate their tax planning with their mortgage planning.
Jo, the business owner faced a sales-tax liability of approximately $347,000. That’s the kind of number that can keep someone awake at night.
We worked through the state’s Offer in Compromise process, examining the taxpayer’s financial circumstances and what could realistically be paid.
The obligation was ultimately resolved for approximately $129,000, payable over 24 months.
That’s a reduction of roughly $218,000.
Now, I want to emphasize something important: not every taxpayer qualifies for an Offer in Compromise, and no professional can promise that result.
But this experience illustrates why you shouldn’t assume that a frightening tax balance leaves you without options.
Before you give up, find out what the law and your financial circumstances actually allow.
Client experience #2 — REPLACE WITH THE FOLLOWING:
Another client worked in credit-card processing and had an IRS installment agreement canceled because of noncompliance.
When that happens, a manageable problem can suddenly become much more urgent.
We worked to bring her back into compliance, address the reasons the agreement had defaulted, and request reinstatement.
The installment agreement was reinstated, giving her a workable path to continue addressing the balance.
The lesson is simple: An installment agreement isn’t just a monthly payment. It’s an ongoing promise to stay compliant.
And if an agreement is terminated, don’t assume there’s nothing you can do. Find out why it happened and whether reinstatement or another collection alternative is available.
An installment agreement is a path forward—but staying compliant keeps you on that path.
“What should someone do first when they receive a tax notice?”
Three things: Read it. Record it. Respond.”
- Read it: Identify the agency, tax year, issue, proposed action, and exact response deadline.
- Record it: Gather the returns, payment confirmations, income documents, and supporting records. Keep a copy of the notice and proof of any response.
- Respond: Contact a qualified tax professional promptly, especially if the notice concerns assessment, appeal rights, a levy, or a terminated payment agreement.
- “What documents help you evaluate their options?” Income and Expense as well as records of charitable giving, medical costs and others
- “What can cause a payment agreement to default?”
Two common reasons agreements default are missed payments and failure to stay current with filing and payment obligations. Getting back into compliance is often the first step toward fixing the problem
- “How do state-tax problems differ from IRS problems?”
Be careful of the technical issues: state tax agencies and the IRS have different procedures and relief programs. Don’t assume that the IRS Offer in Compromise rules govern your state sales-tax example.
- How do you help someone plan for taxes without draining the cash they need for other goals?
Jo, I tell clients that good tax planning isn’t just about reducing the amount of tax they owe. It’s about protecting their cash flow.
We look at estimated payments, upcoming obligations, retirement withdrawals, and major purchases before deciding what makes sense.
If someone already owes back taxes, we evaluate the collection alternatives that may be available based on their actual financial circumstances.
The goal isn’t to promise the smallest possible payment. It’s to develop a lawful, sustainable plan that allows the taxpayer to meet tax obligations while continuing to support their family and financial goals.
A tax plan that leaves you unable to pay your mortgage isn’t much of a financial plan.
(May share later) Charitable giving, QCDs versus other gifts; Nov. 12 Talk Shoppe Old Bag Auction to benefit the Neighborhood Christian Center young people; listener invitation ______________________________________________________
3RD SEGMENT 12 minutes
- ( Small Victories Song playing in background)
For Did You Know today…(see if you can guess the answer before we do)
(JO Garner to present the trivia question)
Trivia Question: Can you guess then name of this well-known Memphis person who had routinely overpaid his taxes to avoid trouble with the IRS
(Ken Sullivan) Hint #1: This famous Memphis person filed his first tax return in 1954.
(Ken Sullivan) Hint #2: This famous person routinely instructed his team to overpay his federal taxes and explicitly refuse entirely legitimate, legal tax deductions. After his passing the IRS still came back trying to get millions of dollars of additional taxes from the estate.
Who is this famous person?
- (Brandie Spicer can give the Answer: Elvis Presley, King of Rock-n-Roll)
- (Ken Sullivan) Jo, Elvis may have been the King of Rock and Roll, but apparently he also believed in paying his taxes! And there’s a lesson there: take every legitimate deduction you’re entitled to, but don’t invent deductions you can’t defend
(Jo) Today on Real Estate Mortgage Shoppe, we are talking about Less Tax Stress, More Home Possibilities
I’m your host, Jo Garner, Mortgage Loan Originator . For your home purchase or a mortgage refinance you can brag about,. We can find the right mortgage product and make the mortgage process EASY on a traditional mortgage, on special programs and outside-of-the-box mortgage programs too. Connect with me at JoGarner.com
Ken Sullivan of Tax Matters Solved 601.421.7848
Brandie Spicer of Howling Wolf Bookkeeping howlingwolfbooks.com
TOPICS COVERED BY JO GARNER, LICENSED MORTGAGE OFFICER
Are you wanting to buy a home but you think you can’t afford it?
Good for you for setting up a realistic budget.
Look for ways that the house you buy can help pay for itself. (Make sure zoning and subdivision restrictions allow your money-making activity)
You can find ideas from our earlier podcasts, but here are a few:
Is the house set up so that you can rent a section of it to a tenant for extra income?
Can you eliminate renting office space and move your office to your home?
Can you operate a money-making hobby from the shop in your backyard or in your garden?
Check out our podcasts on Jogarner.com for more ideas to make your house pay for itself.
Stories of Mortgage Customers Who Broke Through Obstacles to Make Homeownership Possible
Derrylyn Dancy—Help! The higher mortgage rate is a bit daunting
Derrylynn was a young woman on a mission to win in life. One way she knew would get her on track is to stop wasting money renting and put her monthly shelter costs toward owning her own home.
Last year the challenge was finding a house that she really liked. After making offers on houses over a several months, somebody else always offered more money and did not need any help on costs from the seller. She lost out to competitors every time.
This year mortgage rates had gone up a few points higher than last year. In the mid two-hundred thousand price range the payment was over $400 per month higher than it would have been last year. But, she had a better chance of the seller accepting her offer this year
In the professional job where she worked, her income was going up every year. If she could just get the payment down the first couple of years she could enjoy owning the house a lot more.
The answer for Derrylynn? The 2/1 Buydown mortgage. She could enjoy a low payment with a mortgage rate in the low 5’s the first year. The second year the payment would inch up a little higher with a rate in the low 6’s and the third year and thereafter the rate would be in the low 7;s.
Derrylynn consulted with her financial advisors who pointed out that her income was going up regularly to compensate for the payment increase. Based on the current market trends it looked probable that, if she needed to sell the home later, she could sell the home profitably, or use the home for a rental property. Her mortgage was an assumable government product, so there was another possible exit strategy for the future too. In other words, Derrylynn multiple exit strategy possibilities for the future. She also planned to refinance to a much lower fixed-rate mortgage if mortgage rates every dropped back down low enough.
Derrylynn’s realtor negotiated for the seller to pay for the 2-1 Buydown. On a home priced in the mid $200 thousand range, the 2-1 Buydown costs approximately $6,000
Derrylynn saved about a few hundred dollars per month on her payment the first year. She saved a little less the 2nd year. The third year the rate would become fixed.
By starting our with a mortgage rate 2 points lower than the market rate, the home was more than affordable to Derrylynn.
The last strategy was a plan to refinance Derrylynn’s loan when and if the fixed mortgage rates drop back lower one day.
MORTGAGE SOLUTIONS FOR SELF-EMPLOYED BORROWERS
Why writing everything off can lower qualifying income (Does Brandie have a short example story about this?)
Macon and Marta- Mortgage Approval Strategy Moves Outside of the Box
Macon and Marta’s story was similar to Stevie’s story because they owned their own business and wanted to buy a home. Macon and Marta had money saved to put down but two lenders had already turned them down for not showing enough income on the tax returns. Their winning strategy was to use an outside-of-the-box, in-house mortgage that only looked at their business bank statements and not the tax return to determine their income. They had to put down a minimum of 20% to get this loan. The rate was about the same as on a traditional loan and it was a 30 year fixed rate affordable loan.
As a mortgage officer, I have been able to work with so many home buyers or peoplerefinancing who are using outside-the-box mortgage programs. Most of these programs require a minimum of 20% down payment with okay credit. There are loans that verify income with just bank statements, some programs usa simple Profit and Loss Statement, a 1099 or stated income loan. Contact me and we can look for the right mortgage program that works for YOU.
Jo gives some tips on expenses that can lower your tax but still be counted for qualifying income to get a mortgage. “Claim the deductions you are entitled to, report accurately and let us review the financing picture early. The goal is an informed plan.”
Examples of expenses that reduce the taxes you have to pay, but add to the income the mortgage company can use to qualify your loan::
- Depreciation on a car or other asset like a house or equipment.
- Business Use of Your Home
- Depreciable business miles on your car (some programs will allow this and others won’t)
“Two-year lookback” basics Most of the government loan programs require the last 2 years tax returns for self employed borrowers so they can average the net income over two years. . But, if you have been in that business for 5 years or more and have a stable net income, some of the conventional loan products only ask for the most recent tax return. That is really great if you showed more income on your last tax return than on the year before.
FYI We have mortgage programs for self-employed borrowers and also real estate investors that do not use the tax returns at all to verify income. Call me after the show and we can explore how these loans can work for you.
MAKE YOUR PLAN. LET’S WORK YOUR PLAN. IF THE DEAL WORKS FOR YOU TODAY, LET’S DO IT TODAY. I can make the mortgage process easy. Connect with me at www.JoGarner.com You can email me at Jo@JoGarner.com or call me at (901) 482-0354
4th Segment 8 minutes and 50 seconds
(THE SONG- NEW HEIGHTS by Allen McCool allenmccool.com PLAYING IN BACKGROUND ) INSIGHTS & INSPIRATION Jo shares this story
In 1990, a popular country music singer received a crushing blow: the IRS raided his properties and hit him with a massive, life-altering $16.7 million tax bill. They seized his homes, his gold records, and his studios—leaving him with almost nothing.
But, this singer managed to smuggle out his most prized possession: his beloved, battered guitar, Trigger.
Refusing to let despair break his spirit, he went to the IRS with an unusual revenue-sharing proposal.. Armed with only his guitar and his songs, he got an agency to distribute recordings of some of his songs and sold them
In a historic agreement, the federal government split the album sales, and allowed his loyal fans to buy back his seized ranch for him.
By facing his crisis with grit, ingenuity, and a refusal to give up on his art, Willie Nelson almost wiped out all of the IRS debt in 1993 and made a great settlement on what remained. Willie Nelson and his guitar Trigger stood tall and proud against the IRS.
Moral: When life deals you a hard blow and tries to steal away your life dreams, don’t give up. Find people who have conquered what you are going through or someone with a track record of helping someone in your position. Use your resources like Willie Nelson did.
There are professionals right here on Real Estate Mortgage Shoppe today that can assist you with making those smart steps. You don’t have to do it alone.
Today on Real Estate Mortgage Shoppe, we are talking about Less Tax Stress, More Home Possibilities
I’m your host, Jo Garner, Mortgage Loan Originator . For your home purchase or a mortgage refinance you can brag about,. We can find the right mortgage product and make the mortgage process EASY on a traditional mortgage, on special programs and outside-of-the-box mortgage programs too. Connect with me at JoGarner.com
Ken Sullivan of Tax Matters Solved 601.421.7848 DON’T FACE THE IRS ALONE.
Brandie Spicer of Howling Wolf Bookkeeping howlingwolfbooks.com
REAL ESTATE TIP OF THE WEEK 
Brandie Spicer of Howling Wolf Bookkeeping shares a tip –
Tip: Keep your business & personal expenses separated. I don’t mean just on paper. I mean 2 completely different bank accounts separate. Your MLO & your tax prep pro will thank you for it.
Ken Sullivan of Tax Matters Solved share a tip :
Here’s my tax tip for today: Don’t let April 15 be the first day you start planning your taxes.
If you’re self-employed, buying a home, investing in rental property, or approaching retirement, the decisions you make during the year can affect both your taxes and your financial opportunities.
And if you receive a letter from the IRS, don’t ignore it.
Read it, calendar the response deadline, gather your records, and get qualified help before a manageable problem becomes a major one.
Good records protect your deductions. Good planning protects your options. And good representation can protect your peace of mind.
I’m Ken Sullivan with Tax Matters Solved.
Don’t Face the IRS Alone.
Self-employed mortgage qualification: coordinate deductions and financing plans before filing. A deduction that saves you $3,000 in taxes might look a little different if it prevents you from qualifying for the home you want. That’s why the CPA, Enrolled Agent, and mortgage professional need to communicate before the return is filed
Jo Garner Tip: If someone has told you NO on your mortgage request call me or text me there may be a special program or other solution that can work for you
What do YOU want to accomplish with YOUR mortgage? I have the knowledge and experience. Let’s look at traditional mortgage products, alternative mortgage products and even combinations of products. I can help you get you what you need and make the mortgage process EASY. Jo Garner, Mortgage Loan Officer 901 482-0354 www.JoGarner.com
ANNOUNCEMENTS:
Talk Shoppe equips with education, engages by offering connection opportunities between business people and empowers businesses in a supportive community. Talk Shoppe meets every Wednesday 9A-10A CT at Breadie’s Café at One City Church 120 N East Yates Rd Memphis, TN. Thank you to Talk Shoppe’s location sponsor, Breadie’s Café. Happiness and great connections are ahead at Breadie’s Café.
Talk Shoppe on Wednesday October 28th, 2026 9AM “Amazing Referral Race” (part speed networking and part scavenger hunt)
Talk Shoppe says thank you to some of the people who volunteer to help make the free education and networking available to our community. Thank you to these professionals–fractional Certified Financial Officer, Carlin Stuart 901 355-5019. Also, thank you to Winston Gasch of Optim Solutions, builder of AI powered workflows and other apps to HVAC companies and other contractors OptimSolutions.net.
MAKE YOUR PLAN. LET’S WORK YOUR PLAN. IF THE DEAL WORKS FOR YOU TODAY, DO IT TODAY.
Subscribe for weekly Real Estate Mortgage Shoppe podcasts with show notes at www.JoGarner.com
SPECIAL NOTE: REAL ESTATE MORTGAGE SHOPPE DOES NOT ENDORSE 100% OF THE CONTENT ON THIS EPISODE. REAL ESTATE MORTGAGE SHOPPE RECOMMENDS THAT YOU CONSULT WITH A FINANCIAL, LEGAL OR OTHER CERTIFIED, LICENSED PROFESSIONAL BEFORE ACTING OR INVESTING ON ANYTHING YOU HEAR OR SEE FROM THE CONTENT ON THIS SHOW OR BLOG POSTS. THE INFORMATION WE SHARE ON REAL ESTATE MORTGAGE SHOPPE IS GENERAL IN NATURE MEANT FOR GENERAL EDUCATIONAL PURPOSES ONLY, AND NOT AN OFFER TO LEND. EXAMPLES GIVEN FOR ILLUSTRATION PURPOSES ON REAL ESTATE MORTGAGE SHOPPE AND MOST ARE BASED ON TRUE STORIES BUT WE USE FICTIONAL CHARACTERS AND DO NOT DIRECTLY REFLECT REAL PEOPLE OR EXACT DETAILS IN ANY OF THE SITUATIONS. JO GARNER IS A LICENSED MORTGAGE LOAN ORIGINATOR. (EQUAL HOUSING OPPORTUNITY)
- QUOTE CORNER: Robert Knauerhase “Isn’t it appropriate that the month of taxes starts on April Fool’s Day and ends with cries of May Day”
ACKNOWLEDGMENTS AND CREDITS
REJOINDERS:
- Saul Klein, Data Advocate in San Diego, California
- Jackie Woodside, Marlborough, Massachusetts author of “Calming the Chaos”
- Mark Loden, Personal Budget Counselor, Germantown, TN
Transitional Music: First Segment “WAAKA WAAKA” (PD) for Comic Queries; “Small Victories” by Allen McCool allenmccool.com for Did You Know segment; and also the Insights and Inspiration segment “New Heights by Allen McCool For more of his music www.allenmccool.com . INTRO AND OUTRO THEME MUSIC “Country Roads” by Sergie Pavkin
PICK UP YOUR COPY OF “CHOOSING THE BEST MORTGAGE-THE QUICKEST WAY TO THE LIFE YOU WANT” by: JO GARNER
An essential guide for real estate professionals and their customers.
On Amazon and Barnes and Noble
Kenneth G. Sullivan
Post Office Box 1363, Millington, TN 38083-1363
601.421.7848 KSulli8153@aol.com
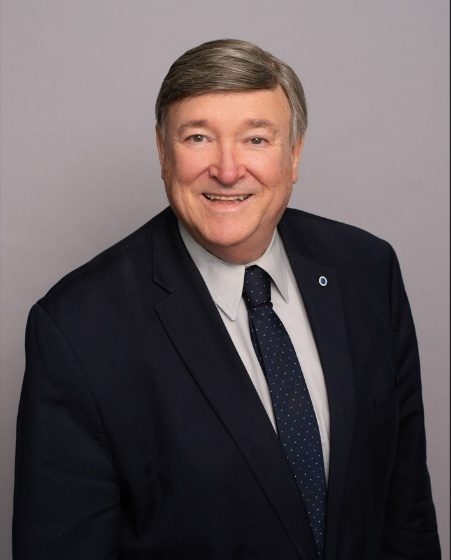
Worked from age 12 as newspaper carrier. Through High School and College.
US Navy Veteran – Small Business Owner – 20+
Exchange Club Member of Clubs in Tennessee and Mississippi.
Past RVP Region 6 – Tennessee and Mississippi (two terms). Past Trustee, National Exchange Club Foundation. Elected National Treasurer July 2023 in Phoenix.
Professionally – Real Estate Broker, license in TN and MS, Tax Resolution Problem Solver. Formerly Area Supervisor for finance company, Management Analyst State of Mississippi, Investor with properties in TN and MS
Family – Married my Bride of 55 years. First born daughter, Doctor of Veterinary Medicine – two grandchildren. Second born daughter, deceased Registered Nurse – two grandchildren.
Education – BBA – University of Mississippi (Ole Miss), SEE (Special Enrollment Examination – Enrolled Agent IRS), USTCP (Practitioner admitted to practice before US Tax Court), CTRS Certified Tax Resolution Specialist.
Interesting factoid – Graduated Ole Miss at age 20
ABOUT JO GARNER-MORTGAGE LOAN OFFICER:
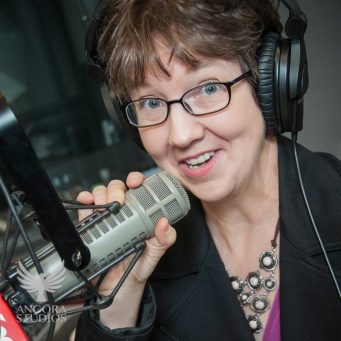
www.JoGarner.com (901) 482 0354 jo@jogarner.com X @jogarner NMLS# 757308 (currently working with Everitt Financial dba Supreme Lending)
ONLINE LOAN APPLICATION : https://jogarner.supremelendingLO.com
“Whatever YOUR personal priorities are, my job is to help you get the mortgage terms that will give you bragging rights when you talk about it and help you score on hitting your goals .”
As a mortgage loan officer, my job is to help you get to the benefits you want from your financing terms. What is most important to you? I can help you find the financing terms that will help you get to what you want. What is your comfort level on a house payment? How much are you comfortable paying down,? What type of financing do you need to get the house you want to buy or refinance?
Different clients have different priorities in life—some are buying their first home with very little down payment funds. Some are recovering from medical challenges, divorces or preparing to send children to college and some are embarking on a long term goal of buying properties to build rental income.”
Jo Garner is a mortgage officer with extensive knowledge in helping her clients find the right mortgage program and making the refinance or home purchase mortgage process EASY. She offers conventional, FHA, VA or other loan programs for primary residences, second homes and investment properties.
Jo can help you look at rent vs buy, when it makes sense to refinance, how to get the best deal on your home purchase financing.
Jo Garner has been in the real estate/financing business for over 30 years. She grew up in West Tennessee and got her start in real estate in Portland, Maine where she first began her real estate career. She received her real estate education from the University of Southern Maine and was personally mentored in San Diego, California by Robert G. Allen, author of Nothing Down, Creating *Wealth and The Challenge.
On moving back to West Tennessee in 1987, she went into business buying and selling discounted owner-financed notes secured on real estate. In 1990 Jo went to work for a residential mortgage company and has been a mortgage loan officer for over 30 years.
In addition to her work in the mortgage field, Jo Garner is the primary sponsor and founder of Talk Shoppe in Memphis. www.TalkShoppe.com Jo Garner also host the radio show Real Estate Mortgage Shoppe airing on the Mighty 990 AM, 107.9 KWAM & streaming on the app https://mighty990.com/app with podcasts and show notes published on www.JoGarner.com Pick up Jo Garner’s book on Amazon or Barnes Noble “Choosing the Best Mortgage-The Quickest Way to the Life You Want”