
Mortgage Rates Are Easing, Home Sales Are Slowing—Where Are the Opportunities?
When the real estate market slows down, who has the advantage—the buyer, the seller, or the homeowner stays put?” The answer depends on the property, the financing, and the homeowner’s goals. “Mortgage Rates Are Easing, Home Sales Are Slowing—Where Are the Opportunities?”
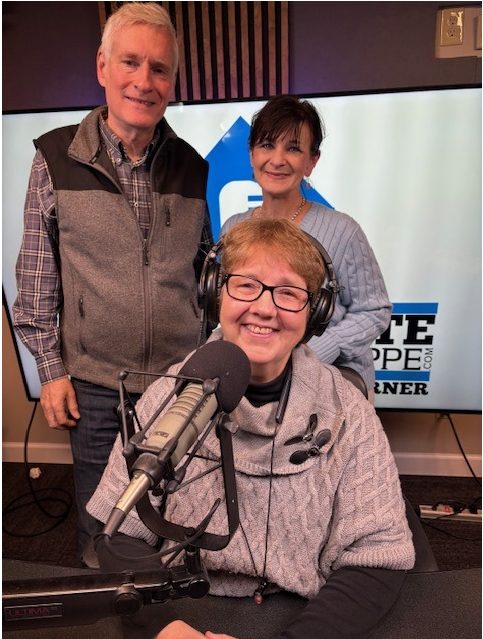
Host: #JoGarner #MortgageExpert 901 482-0354
Co-Host: #AllenMcCool #realestateappraiser Stephenson & Associates 901 763-2100
Featured: #TiffanyThornburg #healthbenefitsmedicare Empowered With Purpose Solutions 901 643-5400
Subscribe at www.JoGarner. Com for weekly Real Estate Mortgage Shoppe podcasts with show notes and pictures.
LET’S GET STARTED…(Jo) (Good morning, Memphis! Welcome to our internet listeners and podcast listeners across the 50 states! . Today is November 7th, 2026. I’m your host, Jo Garner, Mortgage Loan Originator. You can connect with me at www.JoGarner.com. Our general topic “Mortgage Rates Are Easing, Home Sales Are Slowing—Where Are the Opportunities?” Thank you to our sponsors real estate attorneys Rob Draughon and Shelley Rothman of Griffin, Clift, Everton and Maschmeyer Law Firm. For your home purchase or refinance title closing, call Rob and Shelley at 901 752-1133.
Introducing Allen McCool, Appraiser with Stephenson and Associates

Allen McCool, our expert appraiser from Stephenson and Associates is back in the studio. Allen, after decades of appraising homes in the MidSouth, you have experienced ups and downs and changing markets. You have a front row seat to how real estate values affect how people buy and sell homes. . (Allen McCool has about a minute and a half to intro himself and talk about the services he offers his clients )
We are loving our new theme music on Real Estate Mortgage Shoppe written and performed by our own Allen McCool. You can hear more of Allen’s music at www.AllenMcCool.com
(Jo) Remember playing musical chairs when you were a kid? Everybody was moving, the music was playing, and you were trying to find just the right chair! Well, the real estate market can be a little like musical chairs. When the market is moving fast, buyers and sellers are scrambling to make their next move. But when the market slows down, something interesting happens. The BUYER may have more choices and negotiating power. The SELLER may discover creative ways to make their home stand out. And the HOMEOWNER who already has a comfortable chair—with a low mortgage rate—may decide they’re sitting in the best seat in the house!
CONSIDER THESE THREE THINGS IF YOU WANT TO WIN IN THIS MARKET
So, who’s really winning when the real estate market slows down? It comes down to three basic considerations: #1 GOALS-What is your goal and desire for where and how you want to live? #2
FINANCING-What kind of financing will you be leaving if you sell your home? What kind of financing will you be getting where you are buying? #3 What kind of property will meet your needs? Will the location and condition of the property work for you?
If you are buying a home, the first thing to do is to review what your income is –after taxes and other stuff is deducted from your paycheck. What are you spending each month and where are you spending it? Now you know what is the maximum you can afford to pay on a mortgage payment. You will have a better idea how much you can put down on a home purchase and still leave your rainy day fund intact.
BYRON IS A FIRST-TIME HOMEBUYER -HOW HE BRIDGED THE GAP IN WHAT HE NEEDED

First-time homebuyers like Byron usually have the dream or goal they want to achieve but they are short of funds to close and the property they want is a challenge to afford.
Byron’s lease was about to expire on the apartment, and his neighbors had already told him to get ready for a hefty rent increase.
“Not this time,” Byron vowed. Bryon had some credit issues, but he set to work paying down some balances on his credit cards to show that he was using less than 30% of his credit limits on the credit cards. He improved his credit scores which got him better terms on his mortgage. With special lower-than-market interest rates on special mortgage programs and some down payment assistance, Bryon was able to buy his first home with a almost no money down and a very affordable payment. The home was a little smaller than he originally envisioned, but Byron knew how he would make it work until he could move up later on.
ASKING THE SELLER TO PAY $10K IN CLOSING COSTS INSTEAD OF LOWERING THE PRICE $10K
For Barb and Benden, they could afford the mortgage payment on the new home they were purchasing, but they did not want to empty their savings account for the down payment and closing costs. For Barb and
Benden, let’s look at how they came to the right decision really fast. They could buy the house for the seller’s list price of $300,000 and ask the seller pay $10,000 for the buyer’s closing costs. On the day of closing Barb and Benden would realize the full value of the $10k from the seller because they would pay
$10,000 less in full costs at closing. That money could remain in their rainy day fund.
But, because Barb and Benden paid the full price of $300,000 for the home instead of offering $10k less on he price, they would pay an extra $62/month on their mortgage payment because they paid the full price for the home instead of offering only $290,000 and not asking the seller to pay anything for them. It
6 would take over 12 years to realize the full $10,000 value if you were comparing saving only $62 per month. They would probably move and buy another house within 12 years anyway. Paying the higher price and getting the seller to pay the $10,000 in cost would get Barb and Benden the full benefit on day one at closing.
(But of course our appraiser can speak to this scenario. The house would have to appraise for the higher value if Barb and Benden took that option.) Allen, just because some one offers a high price for a home doesn’t automatically mean the house will appraise for that much. Talk about how the comparable sales method works. Also, does the seller paying the $10,000 toward the buyer’s cost affect the appraisal value?) Allen’s responses….
(Jo) Allen McCool, our appraisal expert with Stephenson’s & Association, what are some observations you see? (Allen has about 3 minutes until break to launch his topics)
OUTRO: You’re on Real Estate Mortgage Shoppe. I’m your host, Jo Garner, Mortgage Loan Originator. What do YOU want to accomplish with YOUR mortgage? I can make the mortgage process EASY for you with the right mortgage. Connect with me at JoGarner.com . We will be hearing more from Allen McCool, appraiser with Stephenson & Associates. Also, Tiffany Thornburg of Empowered With Purpose Solutions will be joining us. Stay tuned.
2nd segment is after first break 8 minutes 50 seconds

( Waaka Waaka song in background ) COMIC QUERIES (you probably already know the answer, but we will ask anyway
- (Allen) The market is tough, but I found a small break,
A slightly lower rate for my budget’s sake.
The seller chipped in,
To fund my closing win,
And saved me from a massive financial…(rhymes with break and sake……. ache! - (Jo) Answer last word is ACHE
(Jo) Today on Real Estate Mortgage Shoppe we are talking “Mortgage Rates Are Easing, Home Sales Are Slowing—Where Are the Opportunities?”
I’m your host, Jo Garner, Mortgage Loan Originator . For your home purchase or a mortgage refinance you can brag about,. We can find the right mortgage product and make the mortgage process EASY on a traditional mortgage, on special programs and outside-of-the-box mortgage programs too. Connect with me at JoGarner.com
Allen McCool, Appraiser with Stephenson & Associates 901 763-2100
T ALK SHOPPE TIP
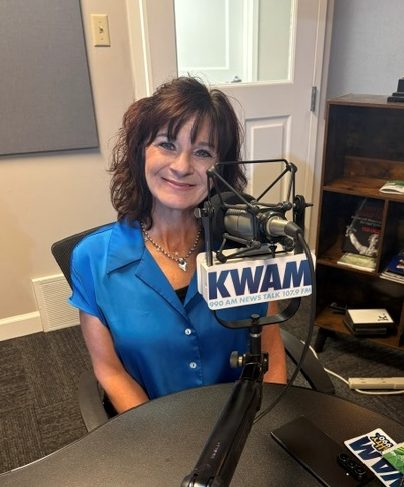
TIFFANY THORNBURG, EMPOWERED WITH PURPOSE SOLUTIONS 901 643-5400
It’s time to talk shop with Talk Shoppe’s Tip . Talk Shoppe is a marketing company offering free education and networking to anyone interested in real estate or in business. Talk Shoppe is made possible by the financial support of its sponsors and advertisers. For more about Talk Shoppe, go to www.TalkShoppe.com (shoppe)
For our Talk Shoppe Tip today we have Tiffany Thornburg of Empowered With Purpose Solutions. Tiffany, your help your clients choose the best health benefits program or medicate plan based on their individual needs. You build your business on the foundation of good relationships. (Tiffany Thornburg of Empowered With Purpose Solutions, what is our Talk Shoppe Tip today?
Tiffany offers her tip: When was the last time you reviewed your medicare plan? Have you seen the prices going up? Other companies offer the same coverage on these programs, but prices to you can vary depending on who you use to get your coverage. Tiffany Thornburg of Empowered with Purpose Solutions is an independent broker and can help you find the better pricing on these products. 901 643-5400
TOPICS BY ALLEN MCCOOL, APPRAISER WITH STEPHENSON & ASSOCIATES
With the market running at a slower pace, there are new strategies and opportunities. In many submarkets, i.e. neighborhoods or sets of competing properties, there is extra inventory, which tends to make sellers more responsive to negotiation.
A powerful negotiation strategy that Jo expertly outlines is that of asking the seller to pay eligible closing costs for the buyer. As Jo explained, leaving a sales price at the asking price, but negotiating seller-paid closing costs for the buyer can save the buyer precious dollars at closing, while having a minimal effect on his monthly payment. Meanwhile, the seller has enabled an eligible buyer who might not have otherwise been able to swing the down payment.
Sellers could sometimes do well offering to consider paying closing costs in their listings, thereby increasing the pool of qualified buyers.
One thing to keep in mind, though, is that this strategy works well when it stays within the limitations imposed by both the lender and the market. The market limitations are where the appraiser comes in.
The bottom line on the market limitation is this: the home must actually be worth the sales price, which in this case is the asking price. Often times, this is true. However, it is a good idea for your strategy to include a contingency for another scenario.
If the home has been on the market an excessively long time, it may be an indicator that the asking price is too high. Appraisers, and savvy buyers, take a look at the days-on-market for the home they are considering, and compare that to the current average days-on-market for the neighborhood or market segment. Of course, closed comparable sales and competing listings are the best indicators of value.
If the combined picture of comparables and relative days-on-market indicates that the asking price is too high, it might be best to offer a realistic purchase price AND ask for seller-paid closing costs. The seller should already know it is taking too long to sell, and could be open to making a deal.
No one has perfect knowledge of the market (not even appraisers, there I said it!), but common sense can oftentimes guide you to a win-win combination.
A stale listing might offer an opportunity, but buyers must distinguish a bargain from an expensive problem.)
- Does a seller concession affect the property’s appraised value?
- Can a home appraise for its contract price even when the seller pays closing costs?
- What is the difference between market value and assessed value?
- Why can online home-value estimates be misleading?
“Your neighbor sold their home for $350,000 last year. Does that mean yours is worth $350,000 today?”
“If a buyer agrees to pay $300,000 for a home, why might an appraiser say it’s worth only $285,000?”
Practical takeaway: An appraisal below contract price can create a problem—or an opportunity to renegotiate.
- What do days on market and price reductions reveal?
- How can sellers distinguish cosmetic improvements from value-producing renovations?
3RD SEGMENT 12 minutes
- ( Small Victories song by Allen McCool playing in background)
- For Did You Know today…(see if you can guess the answer before we do)
(Jo) What was the name of this record company in Memphis, TN?
(Allen) Hint #1: In 1960, a brother and sister, Jim Stewart and Estelle Axton, saw opportunity where others saw an abandoned Memphis movie theater. They transformed it into a recording studio and record shop, listening to the music local customers who congregated there enjoyed hearing.
(Allen) Hint # 2 The marketplace for music was changing. Both black and white musicians came together, creating a sound that changed American music. Jim Stewart and Estelle brought in musicians like Booker T. & the M.G.’s. that created the famous instrumental “Green Onions” released in 1962.
Their lesson? Opportunity often hides in unexpected places. Who was this record company?
(Tiffany) Answer: Stax Records
(Jo) Today on Real Estate Mortgage Shoppe we are talking “Mortgage Rates Are Easing, Home Sales Are Slowing—Where Are the Opportunities?”
I’m your host, Jo Garner, Mortgage Loan Originator . For your home purchase or a mortgage refinance you can brag about,. We can find the right mortgage product and make the mortgage process EASY on a traditional mortgage, on special programs and outside-of-the-box mortgage programs too. Connect with me at JoGarner.com
Allen McCool, Appraiser with Stephenson & Associates 901 763-2100
Tiffany Thornburg, Empowered With Purpose Solutions 901 643-5400
TOPICS COVERED BY JO GARNER, LICENSED MORTGAGE OFFICER

WANT TO BUY A HOME CLOSER TO YOUR FAMILY, BUT CAN’T SELL YOUR CURRENT HOME YET?

Nelly and Nick had been living in the same house for over 20 years. They still owed a little bit on their mortgage but had over $200,000 in equity. For over a year they had been yearning to move out in the country to be closer to their family.
The reason they felt they could not move is because the house they lived in needed some repairs that could not be easily completed until the furniture was moved out of the house. Nelly and Nick wanted top dollar when they sold their old house. They also wanted to put down the $200K equity on the new home so they could enjoy a low payment. But, they could not sell the old house yet until they could do some repairs and fix ups to get the top price. The $200K down payment was tied up in the equity of the old home that they weren’t ready to sell.
I suggested they get an equity line of credit secured as a second mortgage on their old home to use for the down payment on the new home, but they did not want to get a 2nd lien on their old home with a variable rate and the bank would only loan them a portion of the equity.
“If I can show you a way you could enjoy a very low monthly note as if you were putting down the $200K equity for down payment on the new home, would you buy the new home close to your family now?” You can buy the new home now and move out of the old home. You can then fix up the old home and list it for top price.
You can put down the smallest amount of down payment to buy the house close to your family members. Your note on the house will be higher then you want to be at first. When your old house is fixed up and sells, you can pay the $200,000 profit as a prepayment on the new loan we just did. If the new loan was locked with a “recast” situation, the lender will apply the large $200k prepayment to principal and lower the payment calculated on the much lower loan a balance.
The recast would drop Nelley and Nick’s payment on the new home from about $3,000/month to under $1,000/month. They achieved the payment they wanted on the new home, got top dollar for their old home, and now they could afford to spend time and the extra savings making memories with their family.
I have had some of my clients in similar situations, choose to get a lower-than-market mortgage rate on an adjustable-rate loan instead of opting for the recast. Eventually when the old house sells and they prepay the huge prepayment to principal, the mortgage payment is calculated only on the unpaid balance of the mortgage. Depending on the size of the prepayment, the adjustable rate could allow the borrower to pay even less over time than the recast option. Let me know your story and we can project a five to ten year worst cast scenario on the adjustable rate plan to see if it will give you lower payments in the future than the recast option. Either way, you can win.
WHEN THE BUYER AND SELLER BOTH WIN ON THE FINANCING STRATEGY
Mimi Manning (not her real name) had been putting off selling her house in town and moving. Mimi explained to me that she would have sold her house and moved a long time ago but just could not justify giving up the low 3.5% interest rate she had gotten a few years ago on her house.
Mimi told me about the “perfect” house she found. She told me, “But I have gotten so used to paying a 3.5% interest mortgage, I just can’t make myself pay over 6% interest for a new mortgage.
As it turned out, the house Mimi loved, the realtor told me, had an assumable mortgage with an interest rate of a 3.5%.
If Mimi would qualify with the seller’s lender, she could assume and just take over the payments on the assumable loan. Mimi could get a temporary equity line of credit on her old home to pay the seller the difference between the sales price and what was owed on the assumable mortgage.
That is where the seller won on the deal. The seller was able to get the equity they had earned in the home in the cash down payment Mimi paid him. He was able to sell his house quicker because of the assumable loan. If the seller wanted to buy a different home, he could use the equity he got paid from Mimi and put a larger down payment on his next home with a lower loan amount and therefore a lower payment than if he paid less down.
Mimi would have to pay her mortgage on her old house, the payment on the temporary equity line and also the new assumed mortgage on the new home until she could sell her current home. Once she sold her current home, should would, once again, be enjoying the assumed mortgage the seller had gotten years ago at 3.5% interest. No more procrastinating. Mimi was on her way.
TH E FRANKLINS- SHOULD WE STAY IN OUR OLD HOME OR BUY A BIGGER HOME

The Franklin’s decided it would save a lot of money to bring her mother home to live with them. The cash out refinance mortgage gave them the funds they needed to modify the home so her mother and the Franklins could live together but enjoy the privacy of their own space. The money the Franklin’s saved with having their mother in their home versus paying for her to live in an assisted living facility was enough to allow them to hire part-time caregivers for their mother when they needed them.
Other families have shopped around and compared to see if it would be more cost effective to buy a bigger home to accommodate the extra family member or remodel the house where they are currently living to accommodate their mother moving in with them. It comes down to what is the cost to buy a new home—money for down payment and monthly mortgage payment versus the existing mortgage payment on the old home and the payment on the loan to do the remodeling? Which home would make living easier with the extra family member? Compare the financing terms.
For someone like the Franklins, on deciding to stay and renovate their existing home to bring mom home with them, they could have gotten an equity line of credit on their home to do the renovations. They could have looked into how much they could save rolling into the equity line some of the extremely high interest rate credit card debt.
MAKE YOUR PLAN. LET’S WORK YOUR PLAN. IF THE DEAL WORKS FOR YOU TODAY, LET’S DO IT TODAY. I can make the mortgage process easy. Connect with me at www.JoGarner.com You can email me at Jo@JoGarner.com or call me at (901) 482-0354
4th Segment 8 minutes and 50 seconds

(THE SONG New Heights by Allen McCool PLAYING IN BACKGROUND ) INSIGHTS & INSPIRATIONS
Turning the Unseen Opportunity Into A Fortune
Imagine walking into a tech giant during the global calculator price wars, staring at warehouses filled with custom microchips that are about to be thrown out or written off as a complete loss. An entire industry sees obsolete, cheap junk.
But you see a loophole.
You approach the chip manufacturer and make a wild gamble: you promise to buy three million of those “useless” chips over two years, driving the price down to absolute rock bottom. You take that outdated, bargain-bin technology, optimize it for raw speed, and use it to revive a completely dead North American market.
That master of turning cheap tech into a cultural revolution? It was Hiroshi Yamauchi, (hee-ROW-shee Yah ma OO chee) the legendary president of Nintendo, who used low-cost computer chips to build the Famicom and the Nintendo Entertainment System.
Are you wanting to purchase a home or even start your real estate investment business? When others are complaining about the real estate market, look for the opportunities. There are PLENTY of opportunities for first-time homebuyers, move up buyers and investors—home sellers too.
Tell me your story. Let’s explore the best mortgage programs to fit the opportunities you are taking. Connect with me today by calling or texting me at 901 482-0354 or at JoGarner.com
Another new song for Real Estate Mortgage Shoppe by the great composer and performer, Allen McCool. Check out more of his music at AllenMcCool.com
Jo) Today on Real Estate Mortgage Shoppe we are talking “Mortgage Rates Are Easing, Home Sales Are Slowing—Where Are the Opportunities?”
I’m your host, Jo Garner, Mortgage Loan Originator . For your home purchase or a mortgage refinance you can brag about,. We can find the right mortgage product and make the mortgage process EASY on a traditional mortgage, on special programs and outside-of-the-box mortgage programs too. Connect with me at JoGarner.com
Allen McCool, Appraiser with Stephenson & Associates 901 763-2100
Tiffany Thornburg, Empowered With Purpose Solutions 901 643-5400
REAL ESTATE TIP OF THE WEEK
Tiffany Thornburg’s Tip #2 Have you recently signed up for your medicare plan? Did you know that Part A and Part B only cover you for 80% of the costs, but you are still exposed for the other 20% of the cost. But, there are some additional plans that can cover you for that 20% to protect you.
Allen McCool’s Tip : Consult with professionals when you are making decisions about real estate, but also do your own research. When you are thinking about buying a home, check out how many days the house has been on the market. Check out how long other homes in the neighborhood have been on the market. If the house has been sitting on the market a long time, you may have some extra negotiating room.
Jo Garner’s tip :
Even if you are not ready to buy a home yet, if it is in your plan, let’s go ahead and start putting some financing scenarios together to support your plans. Connect with me at www.JoGarner.com (901) 482-0354
ANNOUNCEMENTS:
Talk Shoppe equips with education, engages by offering connection opportunities between business people and empowers businesses in a supportive community. Talk Shoppe meets every Wednesday 9A-10A CT at Breadie’s Café; inside One City Church 120 N East Yates Rd Memphis, TN. Breadie’s is creating a true “third place” for Memphis: the place you want to be when you’re not at home or work. Breadie’s is designed for connection.
Talk Shoppe on Wednesday November 11th, 2026 9AM CT This is the day you can make a positive difference in our Memphis area by coming to bid on mystery purses holding $75 or more in valuable items. This is the Talk Shoppe Charity Auction to benefit the kids at Neighborhood Christian Center.
Join us at Talk Shoppe’s Old Bag Charity Auction to benefit the kids at Neightborhood Christian Center at Wednesday November 7th 9AM CT at Breadie’s Café 120 N East Yates Rd Memphis. Lance Walker of Walker Auctions will be doing a great job as the auctioneer. Channel 24 plans to come out and shoot some of the auction for a feature segment. Come join us to bid on these valuable mystery purses.
(Lynn McDonald’s short segment)
MAKE YOUR PLAN. LET’S WORK YOUR PLAN. IF THE DEAL WORKS FOR YOU TODAY, DO IT TODAY.
Subscribe for weekly Real Estate Mortgage Shoppe podcasts with show notes at www.JoGarner.com
SPECIAL NOTE: REAL ESTATE MORTGAGE SHOPPE DOES NOT ENDORSE 100% OF THE CONTENT ON THIS EPISODE. REAL ESTATE MORTGAGE SHOPPE RECOMMENDS THAT YOU CONSULT WITH A FINANCIAL, LEGAL OR OTHER CERTIFIED, LICENSED PROFESSIONAL BEFORE ACTING OR INVESTING ON ANYTHING YOU HEAR OR SEE FROM THE CONTENT ON THIS SHOW OR BLOG POSTS. THE INFORMATION WE SHARE ON REAL ESTATE MORTGAGE SHOPPE IS GENERAL IN NATURE MEANT FOR GENERAL EDUCATIONAL PURPOSES ONLY, AND NOT AN OFFER TO LEND. EXAMPLES GIVEN FOR ILLUSTRATION PURPOSES ON REAL ESTATE MORTGAGE SHOPPE AND MOST ARE BASED ON TRUE STORIES BUT WE USE FICTIONAL CHARACTERS AND DO NOT DIRECTLY REFLECT REAL PEOPLE OR EXACT DETAILS IN ANY OF THE SITUATIONS. JO GARNER IS A LICENSED MORTGAGE LOAN ORIGINATOR. (EQUAL HOUSING OPPORTUNITY)
(The Auditory version of this disclosure is played during the show)
QUOTE CORNER “If opportunity doesn’t knock, build a door.” — Milton Berle
REJOINDERS:
- Silvana Piadade, EXP Realty 901 647-6661
- Peggy Lau, Viago Travel Cordova Tn 901 289-0747
- Troy and Lynn McDonald of Erin McDonald Insurance Agency 901-849-7101
Transitional Music: First Segment “WAAKA WAAKA” (PD) for Comic Queries; “Small Victories” by Allen McCool allenmccool.com for Did You Know segment; “New Heights” by Allen McCool for Insights and Inspiration segment.
INTRO AND OUTRO THEME MUSIC “Building Value” by Allen McCool www.AllenMcCool.com
PICK UP YOUR COPY OF “CHOOSING THE BEST MORTGAGE-THE QUICKEST WAY TO THE LIFE YOU WANT” by: JO GARNER
An essential guide for real estate professionals and their customers.
On Amazon and Barnes and Noble
 ______________________________________________________________________________
ABOUT ALLEN MCCOOL, APPRAISER WITH STEPHENSON & ASSOCIATES (901) 763-2100

Allen McCool is a real estate appraiser with Stephenson and Associates. Holding the SRA designation from the Appraisal Institute, Allen has appraised residential property in Shelby County, TN for over 35 years, serving a variety of clients, including lenders, attorneys, and individuals. Allen applies a wealth of knowledge and analytical skill to each assignment, provides clarity in reporting results, and is a reliable provider of solutions to challenging real estate problems. 901 550-2100
ABOUT JO GARNER-MORTGAGE LOAN OFFICER:

www.JoGarner.com (901) 482 0354 jo@jogarner.com X @jogarner NMLS# 757308 (currently working with Everitt Financial dba Supreme Lending)
ONLINE LOAN APPLICATION : https://jogarner.supremelendingLO.com
“Whatever YOUR personal priorities are, my job is to help you get the mortgage terms that will give you bragging rights when you talk about it and help you score on hitting your goals .”
As a mortgage loan officer, my job is to help you get to the benefits you want from your financing terms. What is most important to you? I can help you find the financing terms that will help you get to what you want. What is your comfort level on a house payment? How much are you comfortable paying down,? What type of financing do you need to get the house you want to buy or refinance?
Different clients have different priorities in life—some are buying their first home with very little down payment funds. Some are recovering from medical challenges, divorces or preparing to send children to college and some are embarking on a long term goal of buying properties to build rental income.”
Jo Garner is a mortgage officer with extensive knowledge in helping her clients find the right mortgage program and making the refinance or home purchase mortgage process EASY. She offers conventional, FHA, VA or other loan programs for primary residences, second homes and investment properties.
Jo can help you look at rent vs buy, when it makes sense to refinance, how to get the best deal on your home purchase financing.
Jo Garner has been in the real estate/financing business for over 30 years. She grew up in West Tennessee and got her start in real estate in Portland, Maine where she first began her real estate career. She received her real estate education from the University of Southern Maine and was personally mentored in San Diego, California by Robert G. Allen, author of Nothing Down, Creating *Wealth and The Challenge.
On moving back to West Tennessee in 1987, she went into business buying and selling discounted owner-financed notes secured on real estate. In 1990 Jo went to work for a residential mortgage company and has been a mortgage loan officer for over 30 years.
In addition to her work in the mortgage field, Jo Garner is the primary sponsor and founder of Talk Shoppe in Memphis. www.TalkShoppe.com Jo Garner also host the radio show Real Estate Mortgage Shoppe airing on the Mighty 990 AM, 107.9 KWAM & streaming on the app https://mighty990.com/app with podcasts and show notes published on www.JoGarner.com Pick up Jo Garner’s book on Amazon or Barnes Noble “Choosing the Best Mortgage-The Quickest Way to the Life You Want”